October 16, 2026
Export Invoice Factoring: Turn U.S. Receivables Into Cash Flow Faster
International Banking
Fraud Alert: Scammers are texting and calling as TRB’s Fraud Department. TRB’s Fraud Department will never call you, text you a link, or ask for your username, password, or token code verbally or via text. If contacted, hang up and call us at 855-534-4433.


FDIC-Insured – Backed by the full faith and credit of the U.S. Government
One of the most common misconceptions among Mexican businesses selling into the US is that a 60- or 90-day invoice is just the price of doing business. It isn’t. You don’t have to wait on your own money to keep your operation running.
Export invoice factoring lets you convert a receivable from a U.S. buyer into working capital in days, not months, without taking on new debt. If a slow-paying customer is dictating your cash flow, there’s a faster way to run your business.
A 30-, 60-, or 90-day payment term with a U.S. buyer is standard in cross-border trade. It’s also a real strain on working capital. Payroll, inventory, and supplier invoices don’t wait 90 days, even when your customer’s payment does.
There’s a difference between waiting on a receivable and financing it. Waiting means your growth is capped by your slowest-paying customer. Financing means the invoice itself becomes usable capital the day you issue it.
Export invoice factoring isn’t a loan. You’re not borrowing against your business; you’re selling an asset you already have, the invoice, for an advance on its value. That’s the core difference from a traditional line of credit or term loan: there’s no new liability on your books, and approval is based on your buyer’s creditworthiness as much as your own.
Factoring arrangements come in two forms. Recourse factoring means your business is on the hook if the buyer doesn’t pay. Non-recourse factoring shifts most of that credit risk to the factor for approved buyers, typically covering insolvency or default rather than every reason a payment might not arrive. TRB’s export factoring program is structured on a non-recourse basis for approved U.S. buyers, subject to program terms and eligibility. When a Mexican business is selling to a U.S. buyer, having a banking partner that understands cross-border credit and payment practices can make that distinction particularly important.
Selling into the United States adds two layers most domestic factoring arrangements don’t have to account for: currency exposure and cross-border credit visibility.
Currency risk. If your invoice is denominated in dollars but your payroll, suppliers, and operating costs are in pesos, exchange-rate movements can affect the peso value of your U.S. receivables. In addition to export factoring, TRB offers FX solutions that can help Mexican businesses manage currency exposure and gain greater visibility into their cash flow.
Buyer creditworthiness across the border. Vetting a U.S. buyer’s payment history from Mexico isn’t the same exercise as checking a local client’s track record. TRB evaluates U.S. buyers and factoring relationships individually, taking into account the buyer’s creditworthiness and the underlying commercial relationship.
“Don’t let a slow-paying customer decide your cash flow.”
A few signs your receivables cycle is holding back growth:
Before signing with any factor, ask: Is this recourse or non-recourse? What’s the fee structure if my buyer pays late? Can I factor selectively, invoice by invoice, or am I committing my full receivables book?
TRB evaluates each factoring relationship individually, including the U.S. buyer, payment history, industry, invoice terms, and the underlying commercial relationship. For Mexican companies doing business in the United States, factoring can also be part of a broader cross-border banking relationship. Through its International Division, TRB can complement factoring with services such as FX solutions and other banking capabilities designed to support companies as their U.S. business grows.
What’s the difference between export factoring and accounts receivable financing?
Factoring means selling the invoice itself for an advance; the factor owns the receivable and collects from your buyer. Accounts receivable financing means borrowing against your receivables as collateral while you retain ownership and collection responsibility. Factoring typically moves faster and doesn’t add debt to your balance sheet; AR financing is a loan, so it does.
What happens if my U.S. buyer doesn’t pay?
It depends on the agreement. With recourse factoring, your business repays the advance if the buyer defaults. With non-recourse factoring, the factor absorbs that risk for approved buyers, but coverage is typically limited to insolvency or extended non-payment — a dispute over the goods or service themselves usually still falls back to you.
How fast can I get cash from a U.S. invoice?
Once a factoring relationship is established, eligible invoices can be funded after the required documentation, approval, and verification process is complete. Exact timing depends on the transaction and verification requirements.
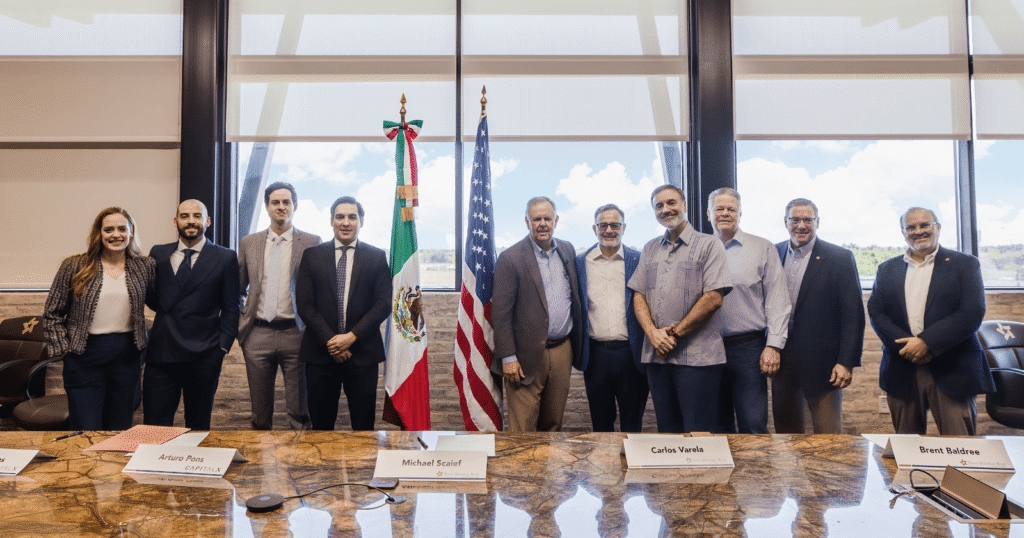
Texas Regional Bank partners with Capital X to deliver cross-border factoring solutions supporting trade between Mexico and the U.S.
Read MoreA slow-paying customer shouldn’t stop you from taking the next order. Export invoice factoring turns a U.S. receivable into cash flow you can actually use, without adding debt or waiting on someone else’s payment cycle.
Don’t let a 90-day invoice determine your ability to take the next order—talk with TRB’s International Division about how export factoring can turn your U.S. receivables into working capital and how TRB’s cross-border banking capabilities can support your business as it grows in the United States.